Those who deliver, win.
Western robotics thinks it has the better product. China already has the factories.
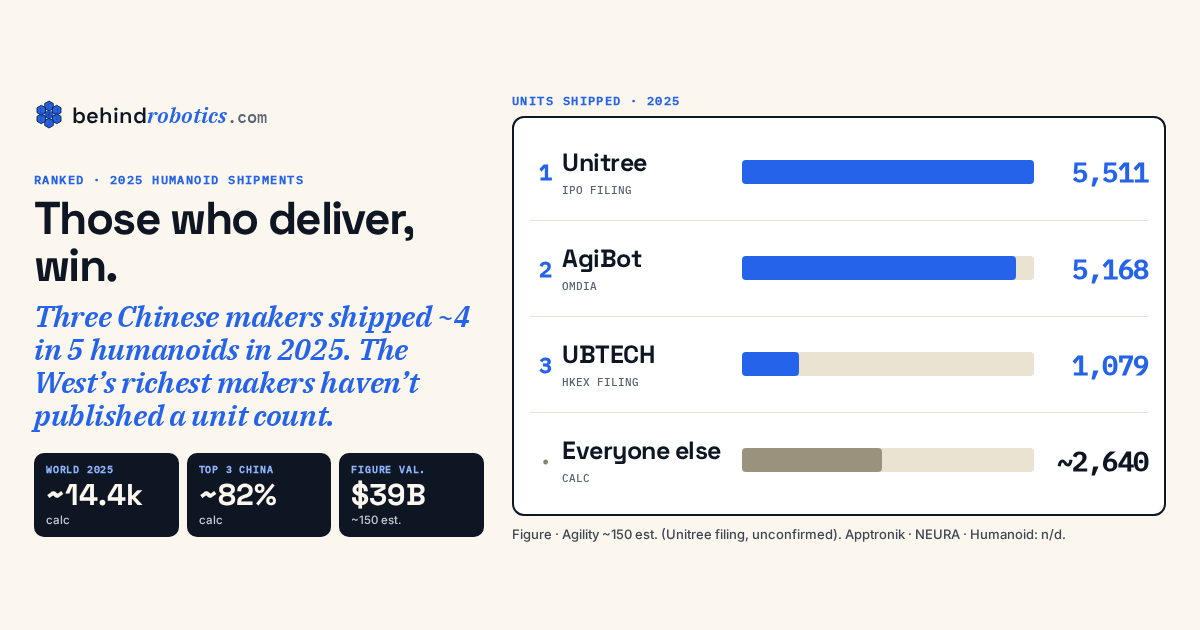
The last time European managers said the disruptor would not scale, it was EVs. Humanoids rhyme. In 2025 three Chinese makers shipped roughly four of every five humanoids on Omdia’s count, while the West’s richest humanoid names still publish valuations and capacity targets, not unit totals.
- Units: Unitree shipped 5,511 humanoids in 2025 (STAR prospectus), AgiBot 5,168 (Omdia) and UBTECH 1,079 (HKEX filing). Together that is ~4 in 5, about 82% of ~14,400 units worldwide (behindrobotics calc: Omdia’s ~13,000 with Unitree and UBTECH swapped to their filed numbers).
- Capital: Figure’s $39B post-money is the biggest Western mark, with no public cumulative sales total. Unitree debuted near ~$50B and was still ~¥249B in late August.
- Plant floor: Chinese makers took 57% of China’s own industrial-robot market in 2024 (IFR), up from ~28% a decade earlier. China is 54% of world installs.
- The rhyme: EVs (manufacturing arrogance) and DiDi vs Uber China (channel). The edge is supply-chain density and a home market that buys at volume, not smarter robots.
It is not a better model. It is a denser factory.
This is not a nationalism slogan. It is an operations claim. Where the buyer is price-sensitive, the business case is winning. Where the buyer is regulated and risk-averse, the West still owns trust. Both are true. The mistake is pretending only one of them matters.
Chinese robot makers took 57% of China’s own industrial-robot market in 2024. That was the first year domestic suppliers beat foreign brands, up from 47% in 2023 and roughly 28% a decade earlier (IFR China release). China installed 295,000 industrial robots in 2024, 54% of global demand. The world’s largest install market flipped its supplier mix.
Reducers, servos and EV-derived motors sit next door. AgiBot’s manufacturing lead has said the company used the NEV supply chain (motors, gearboxes) to scale humanoids fast (China Daily, company). Figure’s own BotQ essay describes the opposite problem in the West: a humanoid supplier tier that is not well established, so Figure builds actuators, motors, sensors, battery and electronics itself (Figure). Agility says about 75% of Digit parts come from the U.S. (Agility). That is a deliberate onshore choice, not an ecosystem that already exists at Chinese density.
Metal shipped vs tickets raised
Three Chinese makers, ~4 in 5 of ~14,400 units
Unitree’s STAR Market prospectus puts its 2025 humanoid shipments at 5,511 (5,716 produced, 5,215 recognised as sales) (Unitree prospectus, p.1-1-143). That makes Unitree #1 and AgiBot #2 with 5,168 on Omdia’s count. Omdia’s earlier estimate had Unitree at 4,200, out of about 13,000 units worldwide (TechNode / Omdia; SCMP). With the filed numbers swapped in, the world total is about 14,400, and the top three Chinese makers shipped ~4 in 5 of it (~82%, behindrobotics calc). UBTECH’s HKEX filing is the other hard number on the board: 1,079 full-size humanoids delivered in 2025, humanoid revenue RMB 820.6M (~US$116M), total revenue RMB 2.001B (~US$282M), net loss RMB 789.8M (HKEX).
AgiBot says it rolled out its 10,000th humanoid around March 2026 and has targeted 10,000 units a year of factory capacity (The Robot Report; China Daily). Unitree told Caixin it had produced about 11,000 G1 units by June 2026 (Caixin). UBTECH claims full-size capacity above 6,000 a year with utilisation under 20% (Humanoids Daily summary of company materials). Capacity is not utilisation.
Now the West’s capital marks. Figure raised more than US$1B at a US$39B post-money valuation (Figure) and targets BotQ capacity of up to 12,000 a year. That is a target, not a disclosed sales total. Apptronik raised US$520M at about US$5B in February 2026 (Reuters); its Mercedes and GXO work is still framed as pilots and R&D. Agility’s SPAC carries a US$2.5B pre-money value, more than US$300M in multi-year Digit orders and Digit at 9 customer facilities (Agility). It is the furthest Western name on paid deployments, yet still without a public thousands-a-year unit total. NEURA’s Series C is up to US$1.4B, at ~US$7B per people familiar (NEURA; Bloomberg via Yahoo). UK-based Humanoid raised US$152M at US$1.35B (Reuters), with a beta aimed at late 2026.
China is not cheap on capital either. Unitree’s STAR IPO priced at about US$9.04B and closed its first day near US$50B (Reuters; Reuters). By late August it had slid, but was still valued at ~¥248.8B (Caixin). AgiBot is reportedly nearing a round at ~RMB 50B (~US$7B), a claim from investors via Caijing (TechNode).
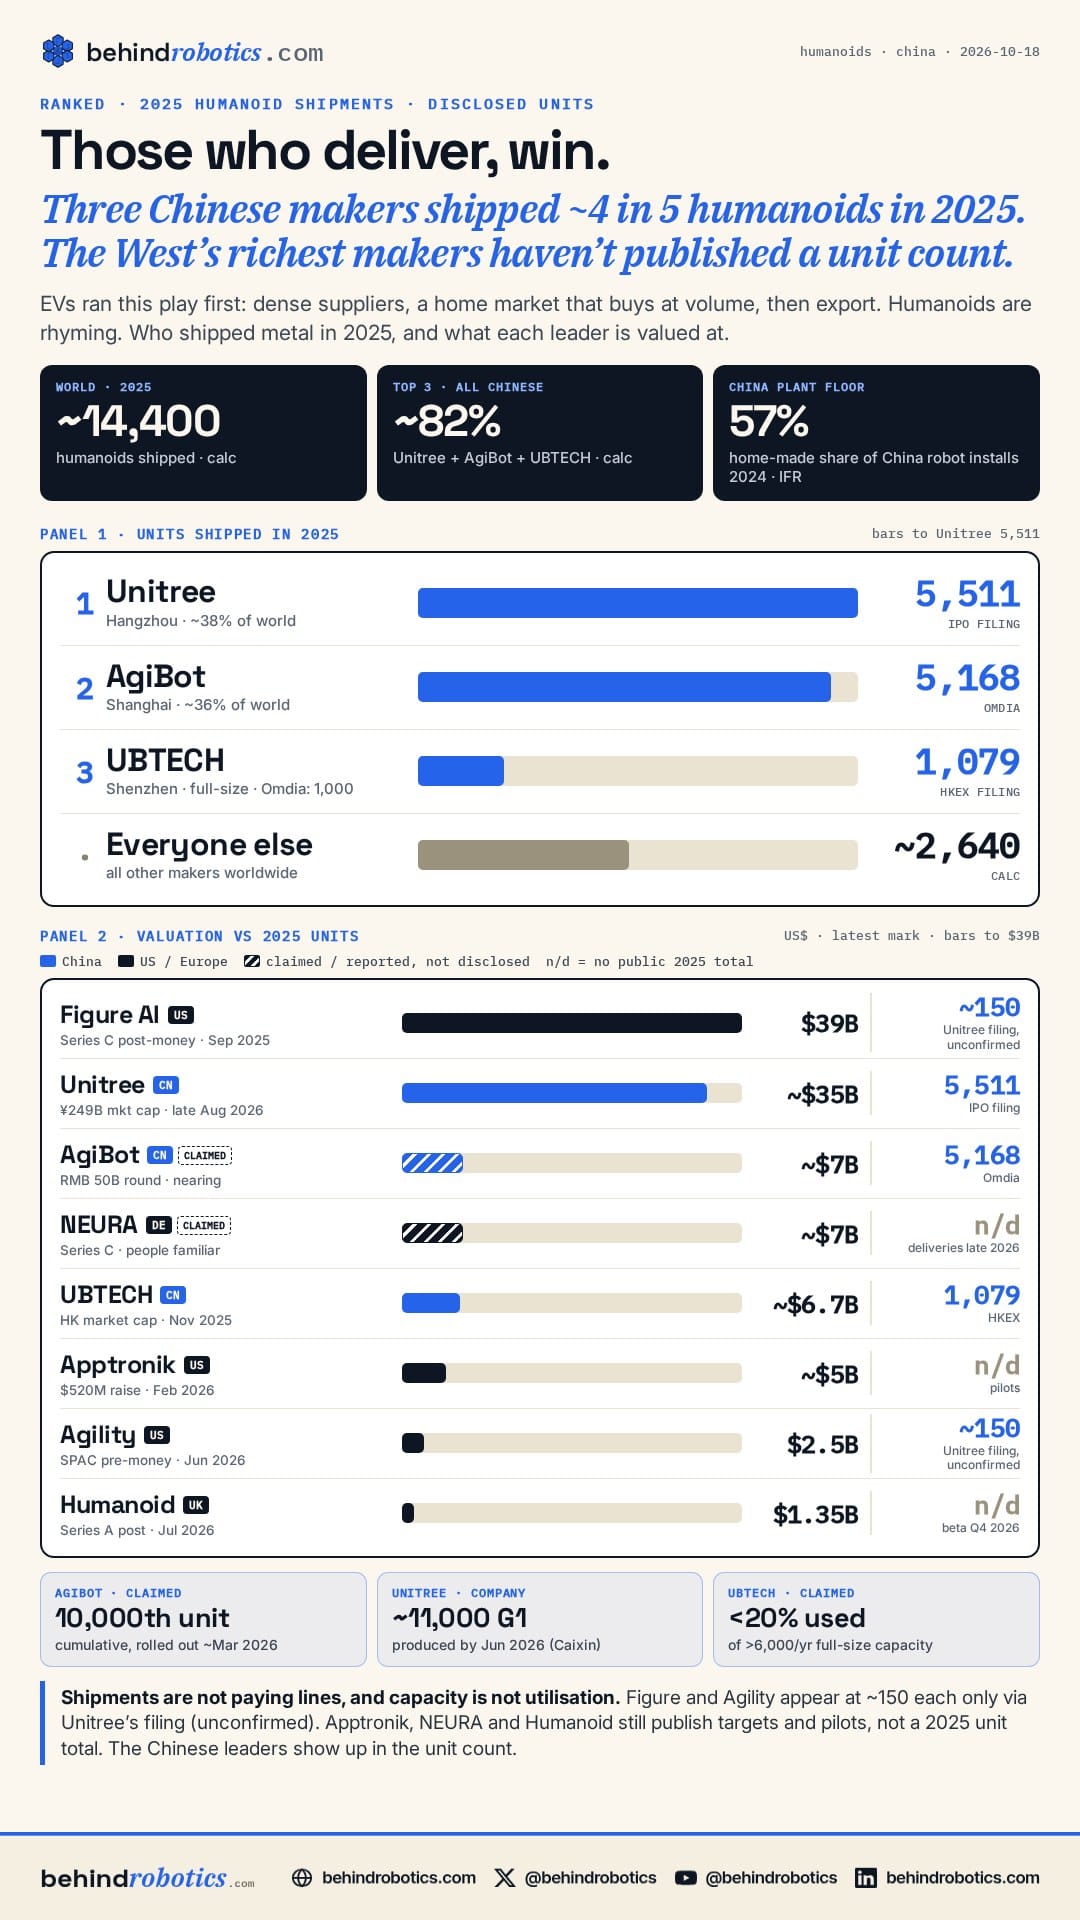
Read the gap carefully. Several Western valuations match or beat Chinese peers while disclosing fewer commercial units. Chinese factories disclose (or claim) thousands of units, while utilisation and paying-line conversion remain open questions. Deliveries are not robots running on a paying line. Funding is not product-market fit. Capacity is not utilisation. Keep all three in the same paragraph, or the chart turns into propaganda. (More context: Chinese makers accounted for more than 97% of humanoid shipments in H1 2026.)
Who still owns the plant floor
Global industrial-robot installations hit 542,000 in 2024. China’s 295,000 were 54% of that, and its operational stock reached 2.027M (IFR; IFR China). Asia took 74% of deployments. Europe and the Americas shrank.
Inside China the mix shifts by vertical. Domestic suppliers took 80% of food-and-beverage installs, 100% of textiles, 90% of metal and machinery and 59% of electronics. In automotive they took only 31%, where foreign brands still hold the trust premium (IFR China). That is the industrial rhyme in one line: Chinese makers win volume on cost-sensitive floors, and foreign brands still win where precision and process risk drive the RFQ.
Broker and MIR notes put Estun at about 10.5% of China robot sales in H1 2025 (company citing MIR), with FANUC near 10.1% and Inovance near 8.9%. Treat those as claimed rankings. Xinhua, citing customs data, reports China’s industrial-robot exports grew 54.9% in Q1–Q3 2025 (Xinhua). We do not claim Chinese welding robots beat FANUC or ABB on reliability; the data for that is not public. What the data shows is domestic share flipping in the world’s largest market, and exports climbing.
EVs first, DiDi second
There is no single perfect “historical mistake” quote. There is a 2010–2013 cluster. Coverage of VW’s Winterkorn era treated batteries as too expensive, range as too short and charging as too slow (SPIEGEL archive). Bosch’s Bohr called EV technology “embryonic” in 2011 and warned against “E-Hype” (Tagesspiegel). Daimler’s Zetsche said in 2013 that EVs were still an “alibi” for German makers (electrive).
Fast-forward: China sold 16.49M NEVs in 2025, exported 2.615M, and NEVs were more than half of domestic new-car sales (CAAM via gov.cn). The mistake was not failing to invent the EV. It was belittling the volume machine that would ship it.
DiDi vs Uber China is the channel lesson. On 1 August 2016 Didi bought Uber China’s assets and Uber took a 17.7% economic interest in Didi (PR Newswire). Local operations, regulatory fluency and channel density beat a stronger global brand. In 2025 DiDi’s core platform GTV was RMB 450.8B, including RMB 117.0B international (DiDi IR).
Humanoids rhyme with EVs on manufacturing arrogance. Industrial robots rhyme with DiDi on channel. Western firms that still treat “better and more reliable tech” as a channel strategy are fighting the last war.
What could break the rhyme
- Certification. CE, UL and ISO still gate EU and US plant adoption. A funding round does not clear a safety audit.
- Export controls. Chips, reducers and sensors can slow Chinese humanoids abroad, and slow Western builds that still rely on Chinese suppliers.
- Geopolitics. A channel can freeze overnight. Dominating China and emerging markets first is a strategy, not destiny.
- Utilisation. UBTECH’s own sub-20% figure is the reminder. Chinese shipment leadership without verified plant uptime is not global lock-in.
Four signals
- Disclosed units on paying lines, not factory tours.
- Chinese suppliers’ share of China’s automotive robot installs (31% in 2024): the trust test.
- Whether Figure, Apptronik, Agility, NEURA or Humanoid publish 2025–2026 unit totals in the same band as Omdia and HKEX.
- Whether Chinese industrial-robot exports keep compounding after the easy share gains at home.
Sources
- IFR, World Robotics 2025 press releases: global · China (PDF)
- Unitree STAR Market prospectus (招股意向书, 2026-07-31), 2025 shipments p.1-1-143: cninfo (PDF)
- Omdia 2025 humanoid shipments (earlier estimate) via TechNode and SCMP
- UBTECH FY2025 annual results, HKEX filing (PDF) · capacity/utilisation via Humanoids Daily (company claim)
- AgiBot: The Robot Report (10,000th unit, company) · China Daily (capacity target, NEV supply chain) · TechNode/Caijing (RMB 50B round, claimed)
- Unitree: Reuters IPO pricing · Reuters debut · Caixin
- Western capital: Figure Series C · Figure BotQ · Reuters on Apptronik · Agility SPAC release · NEURA · Bloomberg via Yahoo · Reuters on Humanoid
- EVs: CAAM via gov.cn · SPIEGEL · Tagesspiegel · electrive
- DiDi: PR Newswire, 2016 · DiDi FY2025 results · Exports: Xinhua